Key Takeaways
- The number of Nigerian workers using pension savings for home equity surged by 284% to 28,437 in Q1 2026.
- The total amount withdrawn for housing equity rose by 228% to N927 billion in the same period.
- This trend underscores the severe housing deficit and declining purchasing power, forcing workers to rely on their Retirement Savings Accounts (RSAs).
- The National Housing Fund (NHF) has largely failed to provide accessible home ownership financing, plagued by administrative bottlenecks and corruption.
- Experts advocate for extending similar housing finance access to Nigerians not covered by the Contributory Pension Scheme (CPS).
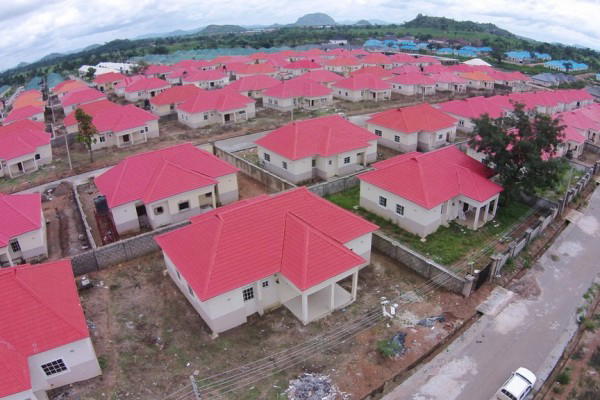
Amidst Nigeria's escalating housing crisis and the relentless erosion of purchasing power, a growing number of workers under the Contributory Pension Scheme (CPS) are increasingly turning to their pension savings to secure residential home ownership. This significant shift highlights the dire need for accessible housing finance and the critical role pension funds are now playing in bridging the affordability gap for many Nigerians.
The country grapples with an estimated housing deficit of 149 million units, a staggering figure that demands an approximate N21 trillion in funding to address. While initiatives like the National Housing Fund (NHF) were established to facilitate home ownership, they have largely fallen short, leaving a substantial void in accessible financing options for the working class.
Recent data from the National Pension Commission (PenCom) reveals an alarming trend. In the first quarter of 2026 (Q1'26), a total of 28,437 pension contributors accessed their Retirement Savings Accounts (RSAs) for home ownership equity contributions. This represents a monumental 284% increase from the 7,399 recorded in the fourth quarter of 2025 (Q4'25).
The financial implications are equally striking. These pension account holders collectively withdrew N927 billion from their RSAs for residential home ownership equity in Q1'26. This figure marks a substantial 227.9% surge from the N28.27 billion withdrawn in Q4'25. Such sharp increases in both the number of participants and the accessed amounts underscore the growing reliance on pension savings as workers struggle to meet the escalating financial demands of home acquisition.
The Contributory Pension Scheme: A Lifeline for Homeownership
The Contributory Pension Scheme (CPS) offers a crucial provision, allowing eligible contributors, known as Retirement Savings Account (RSA) holders, to access up to 25% of their RSA balances as equity contributions for residential mortgage payments. This benefit, enshrined in Section 89(2) of the Pension Reform Act 2014, is available to active RSA holders who have contributed to the CPS for a minimum of 60 months and are seeking to purchase their first home.
PenCom's guidelines meticulously outline the process: if 25% of the RSA balance exceeds the required equity contribution, the RSA holder can only access the amount equivalent to the equity needed. Conversely, if 25% is insufficient, the RSA holder may utilize Voluntary Contributions (VC) or, for Personal Pension (PP) contributors, their contingency portion. Should these options still fall short, the RSA holder is required to deposit the difference with the mortgage lender.
The Persistent Failure of the National Housing Fund
Despite its laudable objectives, the National Housing Fund (NHF) has largely failed to deliver on its promise of accessible home ownership. Joe Ajaero, President of the Nigeria Labour Congress (NLC), highlighted significant issues, noting that while the government consistently deducts the mandated 2.5% from workers' salaries, the Federal Mortgage Bank of Nigeria often fails to inform workers about deposits into their NHF accounts. This lack of transparency, coupled with administrative bottlenecks and perceived corruption, has created immense frustration.
Ajaero lamented, "Administrative bottlenecks in the process of accessing the mortgage scheme have created room for corruption in the system. While the Act provides for 90 days from the date of application for the loan to disbursement, the experiences by many workers are horrific as the undue delay in approving the loans forces many workers to abandon pursuit of the loan." He added that many resort to third-party agencies, paying unofficial fees to fast-track applications, further entrenching corruption.
Expert Perspectives: Economic Headwinds and Solutions
Industry experts universally acknowledge the increasing role of RSA balances in supporting access to affordable housing. Mr. Michael Simire, an Urban Planner, pointed to naira devaluation and the worsening economic situation as primary barriers to home ownership. He noted that while money might not be readily available for investment, the pension scheme is making home ownership possible for many, despite numerous vacant properties that remain unaffordable.
Mr. Ivor Takor, Director of the Centre for Pension Rights Advocacy, commended the inclusion of home ownership in the pension scheme. He further advocated for extending similar financial assistance, such as loans at moderate interest rates, subsidies, and tax concessions, to Nigerians not covered by the pension scheme. Mr. Meckson Innocent Okoro, Principal Partner of MI Okoro and Associates, echoed these sentiments, stating that the current economic climate has led to low demand and supply in the real estate sector, with high exchange rates pushing up costs and extending payback periods. He anticipates that the pension scheme's involvement will lead to moderation in pricing and a boost in home ownership.
Former President of the Pension Fund Operators Association of Nigeria (PenOp), Mr. Olumide Oyetan, emphasized the positive impact of the residential mortgage scheme, stating, "The successful implementation of this initiative would improve people's welfare and move the country forward."
Why This Matters
The dramatic increase in pension withdrawals for home equity underscores a critical intersection of Nigeria's housing crisis, economic challenges, and the evolving role of its pension system. While providing a much-needed lifeline for many, this trend also highlights the systemic failures of traditional housing finance mechanisms and calls for broader, more inclusive strategies to ensure affordable housing for all citizens, both within and outside the Contributory Pension Scheme.