Key Takeaways
- Finance Minister Taiwo Oyedele warns that reinstating petrol subsidy could devalue the naira to N3,000-N4,000 per dollar.
- Such a move would trigger significant capital flight and erode investor confidence in Nigeria's economic stability.
- Oyedele emphasized the government's unwavering commitment to its economic reforms, ruling out any reversals.
- He clarified that the Nigerian National Petroleum Company Limited's (NNPCL) temporary reduction in petrol retail margins is a commercial decision, not a return to subsidy.
- The minister highlighted that both domestic and international markets have largely dismissed the opposition in Nigeria as being unserious regarding economic policy.
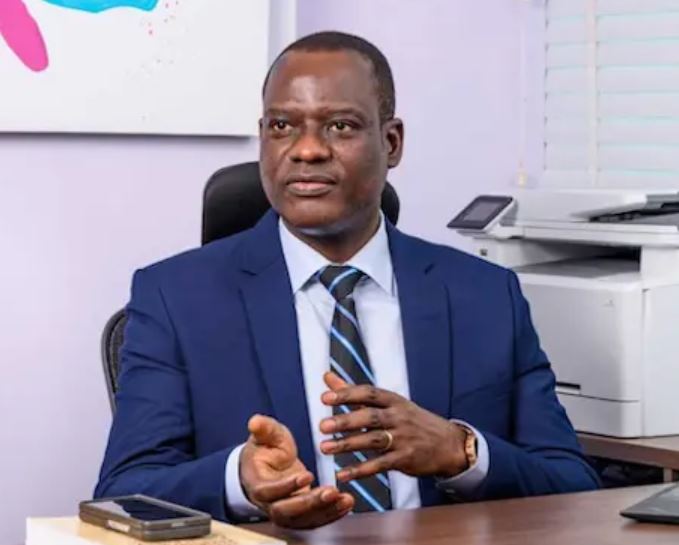
Nigeria's Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has delivered a stern warning against any consideration of reinstating petrol subsidies, cautioning that such a move could unleash severe economic repercussions. Speaking at a press briefing during the International Monetary Fund (IMF) and World Bank Annual Meetings in Bangkok, Thailand, Oyedele projected that a return to subsidies could trigger widespread capital flight, significantly weaken investor confidence, and potentially push the naira's exchange rate to an alarming N3,000 to N4,000 against the US dollar.
The minister's remarks underscore the Bola Tinubu administration's commitment to its economic reform agenda, which notably included the removal of the long-standing petrol subsidy on May 29, 2023. This decision, while initially causing hardship, was aimed at freeing up crucial government funds and addressing the unsustainable burden the subsidy placed on national finances. Oyedele revealed that investors, both domestic and international, have consistently questioned the government's resolve to maintain these reforms, particularly with the next election cycle on the horizon.
Oyedele unequivocally ruled out any reversal of the reforms. He stressed that even a mere signal that President Bola Tinubu’s administration was contemplating reinstating the petrol subsidy could send shockwaves through financial markets, leading to increased borrowing costs for the government and exacerbating economic pressures on Nigerian households. “In all the meetings I have had, I came to a conclusion that the markets, including the domestic market, which you can read from the capital market, and the international market, have largely written off the opposition in Nigeria as being unserious,” he stated, highlighting the perceived lack of credible alternative economic policies.
The minister further elaborated on the immediate and drastic market reaction such a policy shift would provoke. “If, for any reason, the President were to say we are merely considering the return of fuel subsidy, capital would react immediately. Airfares would struggle, the naira would come under severe pressure, potentially moving towards 3,000, 3,500 or even 4,000. The very fuel people want subsidised would become far more expensive in naira terms,” he warned. This scenario would not only impact foreign investors but also prompt wealthy Nigerians, business owners, and middle-class investors to convert their assets to dollars as a hedge against uncertainty, further intensifying demand for foreign exchange and depleting national reserves.
Addressing recent speculation, Oyedele also dismissed suggestions that the Nigerian National Petroleum Company Limited’s (NNPCL) temporary reduction in petrol retail margins amounted to a return to subsidy. He clarified that this was a commercial decision by the company, not a payment funded by public resources. He argued that a company's choice to lower its profit margin to make a product more affordable should not be automatically classified as a subsidy, which typically involves government financial intervention.
Why This Matters
Minister Oyedele's strong warning highlights the critical importance of policy consistency and fiscal discipline for Nigeria's economic stability and growth. A reversal of the petrol subsidy removal would not only undermine investor confidence and trigger a severe currency crisis but also jeopardize the nation's long-term economic recovery efforts, ultimately burdening the very citizens it purports to help with runaway inflation and diminished purchasing power.